What’s inside WhatsApp’s new Payments section
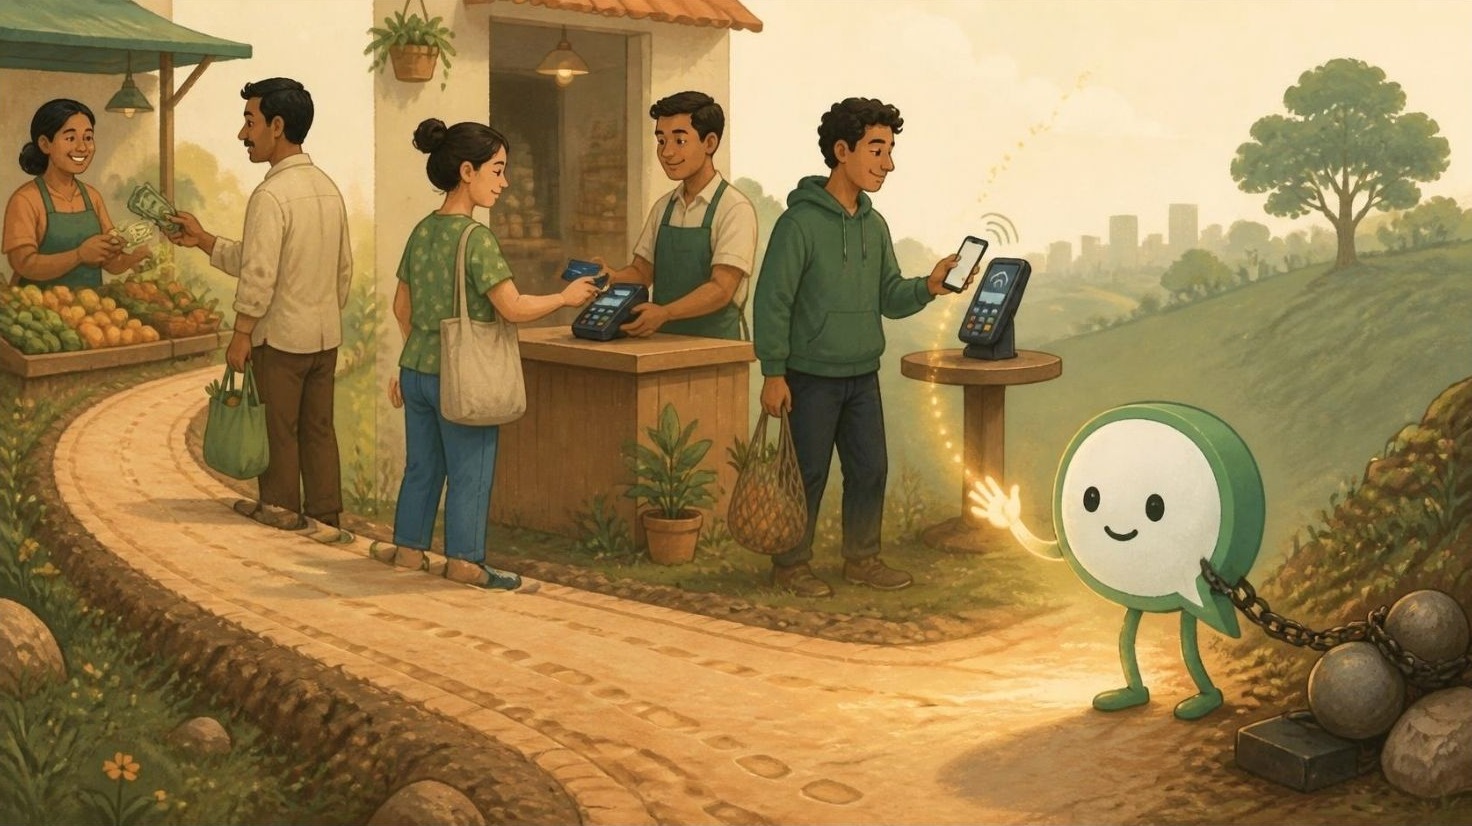
WhatsApp is back at work on in-chat payments, and this time Italy is among the possible markets. The feature surfaced in the code of the iOS beta 26.33.10.70, where it’s still under development and hasn’t reached beta testers yet. The screen has three areas: sending money to a contact, adding a credit or debit card by entering its number, expiration date and CVV, and finally shipping details such as email, phone and address. The billing country selector lists the Netherlands, Australia, Austria, Canada, Germany, Ghana, Italy, Spain and the United States, though WhatsApp hasn’t confirmed any expansion plans.
I spent twenty years in the payments industry, many of them at PayPal, and my first reaction to this news was a fond kind of skepticism, the kind you develop after watching plenty of triumphant announcements end up in a drawer. In my view, habit outweighs any new feature, and the window for entering this market closed a while ago.
A new boss with a fintech background
The timing has an explanation. Meta has named Kunal Shah, founder of CRED, as the global head of WhatsApp: he replaces Will Cathcart, and the move comes with a $900 million investment in CRED, roughly a 20% stake. The announcement came on June 22, 2026, and the message is fairly clear: monetize three billion users through their wallets. The same wire story noted that in India, analysts believe WhatsApp has largely missed its chance to build an equally popular payment service.
In India, WhatsApp plays at home and finishes eighth
India is the textbook case. WhatsApp Pay has been live there since 2020, runs on the national UPI network and starts from more than half a billion users. Even so, in July 2026 it processed about 168 million transactions, ranking eighth among UPI apps. That’s real growth, but it needs perspective: in the same month PhonePe’s volume was more than 64 times higher, and Google Pay’s more than 45 times. The two leading apps together controlled 79% of the market in May.
The lesson is simple: having everyone in your contacts isn’t enough. People who have already picked how they pay rarely switch for marginal convenience, even when the newcomer lives inside the app they open fifty times a day.
In Italy, habits have already picked their tools
Italy is often described as the last holdout for cash, but the data shows a transition well underway. According to the Innovative Payments Observatory at Politecnico di Milano, in 2025 electronic tools settled 45% of consumer spending, against 38% for bills and coins, and 14 million people paid with a smartphone or wearable over the past year.
The catch for WhatsApp is that even money transfers between friends already have their channels. In 2025, 69% of Italians used instant bank transfers at least once. Satispay, with 6.5 million users and more than 450,000 affiliated merchants, has captured a sizable share of the public, especially in large cities, where splitting a bill or paying at the café through the app has become a routine gesture. Then there’s PayPal, which has handled person-to-person transfers flawlessly for a long time, even though many people still associate it only with online shopping: I admit a touch of bias, having worked there for years, but it’s a feature that deserves more recognition. Rounding out the picture, Bancomat Pay has been talking to Spain and Portugal since Bancomat, Bizum and SIBS launched EuroPA in November 2024. In other words, there’s little free space left, and those who hold it spent years building agreements with banks and merchants.
Apple Pay and Google Wallet won because they live in the phone
Apple Pay and Google Wallet also struggled to win Italians over. For years they remained tools for tech enthusiasts, until widespread contactless terminals and cards already stored on the device made the gesture feel natural: in my case, one tap, I hold the phone near the reader and the purchase is done. Their strength has always been integration into the operating system, that seamless effect no third-party app can fully replicate. I wrote about it when looking at how Google Wallet is turning into a super-app.
WhatsApp starts at a disadvantage on exactly this ground. Judging by the beta, it will ask users to type in card number, expiration date and CVV by hand, a step phone wallets did away with long ago. And then there’s ecosystem fatigue: every platform wants to become the app that does everything, and we end up with apps trying to be all things to all people, all competing for the same everyday gestures.
Stolen accounts and spyware: trust is the sticking point
The second obstacle concerns perceived security. In Italy, the best-known WhatsApp scam involves the verification code: the Postal Police have warned about messages along the lines of “Hi, I sent you a code by mistake, could you send it back?”, which scammers use to take over the account and the contact list. Today the damage amounts to digital identity theft and a chain of scams aimed at contacts. With a card saved in the app, the same theft would turn straight into a financial problem.
Then there’s the Paragon case. In early 2025, WhatsApp itself announced that the Israeli spyware Graphite had targeted around ninety users, activists and journalists among them, through a zero-click attack, and the victims included Fanpage editor Francesco Cancellato. To be fair, it was WhatsApp that discovered and neutralized the exploit, yet what sticks in users’ minds is mostly the story of phones being spied on. Having written about my reluctance to hand my passwords over to AI, I’ll confess similar reservations about financial data inside a chat.
Meta and money, a complicated story
The company’s past weighs in too. In 2019 Facebook unveiled Libra, a digital currency with global ambitions, later renamed Diem to appease regulators. It wasn’t enough: in early 2022 the association sold its assets to Silvergate, explaining that its dialogue with federal authorities had made clear the project couldn’t move forward. People in payments remember that episode well, and so, above all, do European supervisors. Meta isn’t the only social media giant chasing users’ wallets: Elon Musk is trying too with X Money, and there as well, trust matters as much as technology.
What could flip the forecast
In fairness, there are a few arguments in WhatsApp’s favor. The first is conversational commerce: in Brazil, millions of small businesses use WhatsApp to send catalogs and offers, and in Mexico registered businesses can already accept payments directly in conversations. In Italy too, plenty of neighborhood shops, hair salons and craftspeople handle orders and appointments over chat; closing the transaction in the same place would make some sense. The second is Kunal Shah, who proved with CRED that he can build financial products around user loyalty.
Still, payment habits change slowly and rarely, and in Italy nearly every seat at the table is already taken. For now, I wouldn’t put my card into WhatsApp, at least not among the first. We’ll keep an eye on it.
Related sources
- WhatsApp may expand payments to more countries, WABetaInfo, August 2026
- WhatsApp prepara una nuova sezione Pagamenti, HDblog (in Italian)
- WhatsApp Payments: pagamenti in-app anche in Italia?, Punto Informatico, August 2026 (in Italian)
- Meta Appoints Kunal Shah As WhatsApp Leader, RTTNews on Nasdaq
- WhatsApp Pay Doubles UPI Transactions To 168 Million, The Logical Indian
- Pagamenti digitali in Italia: record di 518 miliardi, Innovative Payments Observatory, Politecnico di Milano (in Italian)
- Pagamenti digitali: cosa sono e come funzionano, Innovative Payments Observatory (in Italian)
- Satispay, nuovo aumento di capitale fino a 120 milioni, Teleborsa (in Italian)
- Postale: attenzione al link truffa di WhatsApp, Polizia di Stato (in Italian)
- WhatsApp dice che oltre novanta giornalisti e attivisti sono stati spiati sulla sua app, Il Post (in Italian)
- The end: Facebook-backed digital currency Diem sold to bank, AP via Business Standard
